Superbank looks beyond credit scores with AI
The bank monitors its lending models for bias and performance.
PT Super Bank Indonesia is using artificial intelligence (AI) and customer behaviour data to assess borrowers overlooked by conventional credit scoring, letting it develop lending products for underserved segments whilst managing risk.
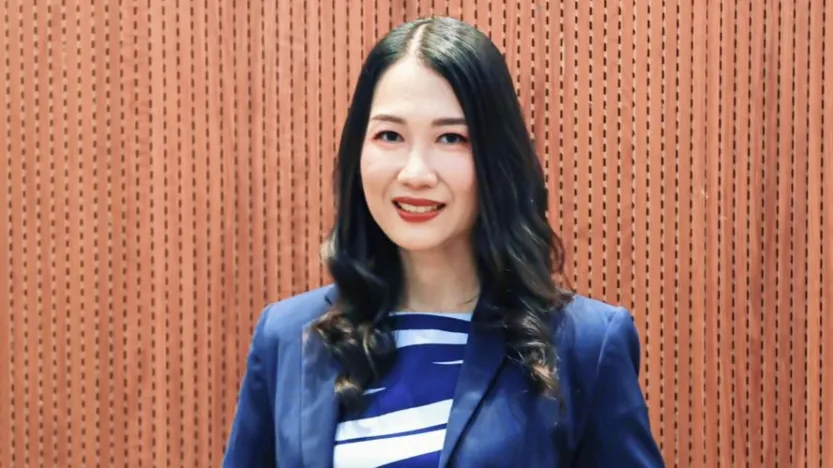
“AI and analytics can help us analyze a broader range of customer and behavioral data to identify patterns that may not be captured through traditional credit assessment approaches,” Melisa Hendrawati, chief financial officer at Superbank, told Asian Banking & Finance.
Indonesia’s third-biggest digital bank by assets uses those findings to group borrowers by risk, design credit products, set lending conditions, and adjust its credit strategy.
Hendrawati said Superbank tests lending assumptions, monitors customer behaviour, and uses the results to refine products, shortening development time whilst improving its assessment of borrowers.
AI does not replace human judgement in credit decisions, she said. The bank continues to monitor its models for bias and performance, ensuring they comply with regulatory requirements and its lending risk limits.
Superbank also requires every AI project to have a defined business objective and measurable targets before approval.
“Organisations must know the business outcome they want out of AI, otherwise it's just a good buzzword,” Hendrawati said in an emailed reply to questions.
The bank first identifies the customer or operational problem a proposed tool will address, then tests it through pilot projects. Wider deployment depends on whether it meets predetermined performance targets.
For lending, Superbank measures AI's contribution through better credit risk assessment, faster product development, and its ability to serve customers who are difficult to assess using conventional models.
The bank also considers operating costs, customer engagement, and employee productivity when evaluating AI investments.
Oki Stefanus, Partner at PT Ernst & Young Indonesia, said banks must demonstrate that AI improves lending profitability and controls credit risks, rather than simply cutting costs, to convince boards and investors of its value.
“A strong business case is not only about raising the approval rate, but also about proving that credit growth can deliver a better risk-adjusted return than conventional approaches,” he said in an emailed reply to questions.
Stefanus said banks should assess AI investments over the medium to long term because benefits might take time as they improve their data, risk models, and operations.
Access to alternative credit data alone does not give lenders a lasting advantage, he said. Most banks can obtain information from Indonesia’s credit information system, private credit bureaus, and other sources.
The advantage comes from using that information to make better lending decisions, improve risk assessments, and keep loan quality and profitability.
Digital banks can experiment faster and make greater use of data, whilst conventional banks have stronger funding, more experience managing risks, and broader customer relationships, Stefanus said.
“It is not simply the one with the best technology that will win, but the one that can translate that technology into sustainable growth while keeping asset quality intact,” he added.
Stefanus said banks should test AI tools and lending products on a limited scale, with risk management, legal, and compliance teams involved from the start. Banks should set limits on lending exposure, target borrowers, and acceptable risks before expanding successful trials.
Hendrawati said Superbank's digital-first structure makes it easier to integrate data across departments, although AI must remain subject to risk management, data protection, and regulatory controls.
“AI is not a business strategy by itself; it is an enabler,” she said. “The real differentiator lies in how effectively an organisation applies AI to solve meaningful business problems and deliver better outcomes for customers and the business.”
 Read Here
 Advertise
 Sign Up