BSP sees lower transfer fees boosting digital payments, deposits
Some banks reported digital transactions rising by as much as 50%.
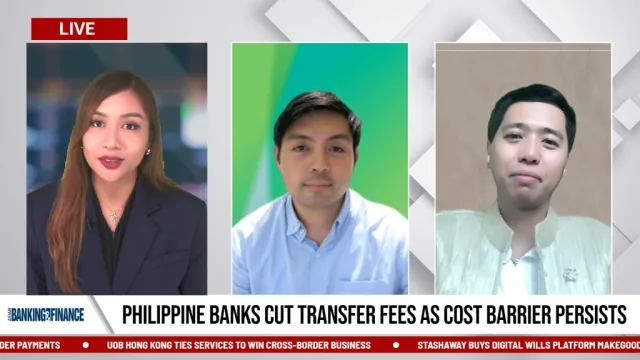
The Bangko Sentral ng Pilipinas (BSP) expects banks’ lower interbank transfer fees to increase digital payment use and help them attract and retain deposits.
More transactions can create opportunities for institutions to deepen customer relationships and attract or retain deposits, Mamerto Tangonan, deputy governor for the payments and currency management sector at the Philippine central bank, told Asian Banking & Finance.
“Sustainable earnings should come mainly from deeper customer relationships and services such as lending, investments, insurance, and other financial products,” he said in an emailed reply to questions.
BSP Circular No. 1238, issued in June, requires banks and payment service providers to justify differences between their transfer costs and customer fees.
Tangonan said the central bank found a gap between the switch cost, which it estimated at $0.024 (P1.50), and fees charged by banks, at $0.16 (P10).
Transfers within and between banks and e-wallets have the same underlying costs, except for the switch cost, he said.
The circular has prompted major local banks, including Bank of the Philippine Islands, Inc. and Metropolitan Bank & Trust Company, to remove interbank transfer fees.
BPI President and CEO Jose Teodoro Limcaoco said in a July 1 statement that lower fees could encourage customers to make digital transfers more often.
Some institutions that cut or waived transfer fees have reported digital transaction increases of as much as 50%, Tangonan said.
“Transaction fees consistently rank among the main reasons Filipinos do not use digital payments,” he said.
Banks can offset lower fees through higher transaction volumes, economies of scale, and sales of other payment and financial services, Tangonan said.
These services include merchant and corporate payments, cash management, card payments, lending, deposits, and other value-added services.
Lower fees could also help rural and thrift banks expand their reach and compete with commercial banks with bigger branch networks, Tangonan said.
Banks should not recover lower transfer fees by raising fees or spreads on other products, he said. All bank pricing decisions must be justified to the BSP, not just transfer fees.
Tangonan said the circular followed consultations with the banking and payment industry. The circular does not require banks and payment service providers to cut or eliminate transfer fees. They can set their own fees if pricing is reasonable, fair, transparent, and based on costs, he said.
A P10 transfer fee is not automatically allowed or prohibited, Tangonan said. Banks must show the BSP that the fee, including differences between transfers within the same bank and transfers to other banks, is reasonable and backed by documented costs.
Volume caps on free transfers, such as those imposed by Rizal Commercial Banking Corp., are also not automatically noncompliant, he said. Fees charged after customers exceed those caps must comply with Circular No. 1238.
 Read Here
 Advertise
 Sign Up