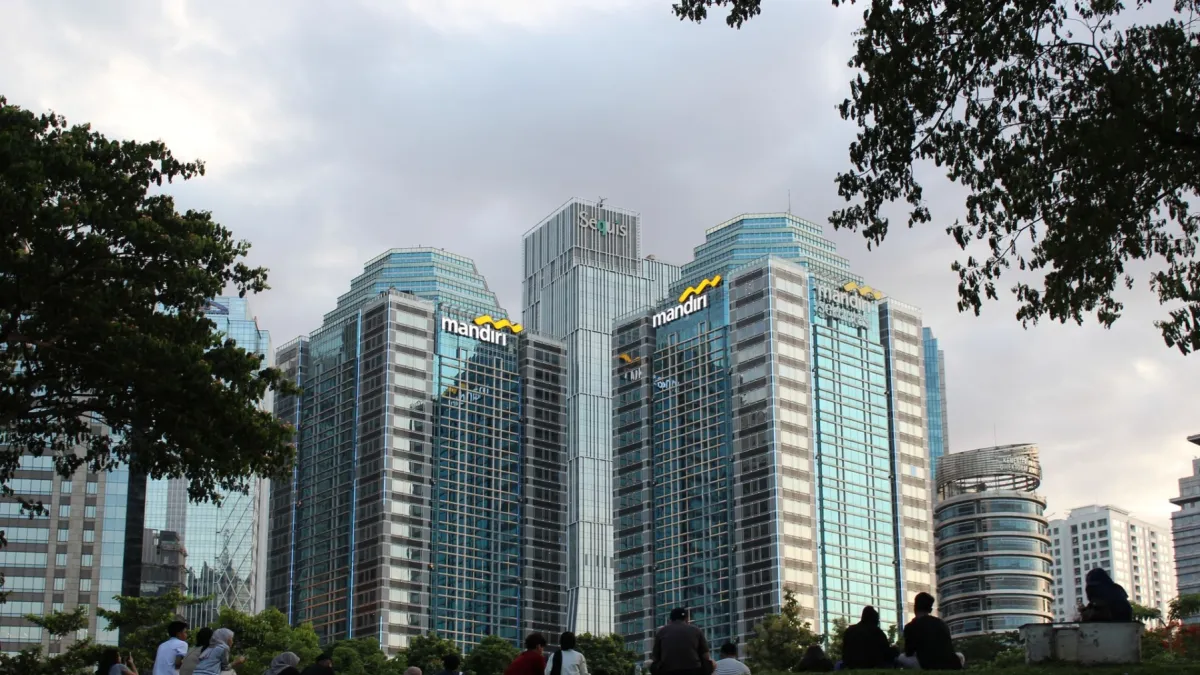
Bank Mandiri margins seen falling to 4.1% as funding costs bite
Margins could improve in Q4 but will depend on funding conditions, UOBKH said.
Bank Mandiri’s management expects its net interest margin (NIM) to decline to 4.1% in Q3 2026, from 4.37% in H1, as funding costs remain elevated.
The Indonesian bank is building provision coverage for corporate exposures, with management expecting its cost of credit to end in the upper end of its earlier 60 to 80 basis points (bps) guidance, or 0.6% to 0.8% of loans, said UOB Kay Hian (UOBKH).
For 2027, management is guiding a cost of credit between 80 to 100bp.
Margins could improve in Q4, but it will depend on funding conditions, UOBKH said.
Bank Mandiris’ capital is another cause for consideration, said UOBKH, with the bank common equity tier 1 (CET1) ratio declining to 16.4% in H1 partly due to dividend payments.
“Subsequent earnings retention could support capital rebuilding, although the extent will depend on loan and risk-weighted asset growth,” UOBKH said.
 Read Here
 Advertise
 Sign Up