India draws foreign banks as China expansion remains costly
Setting up a Chinese unit requires $149m in capital, versus $53m in India.
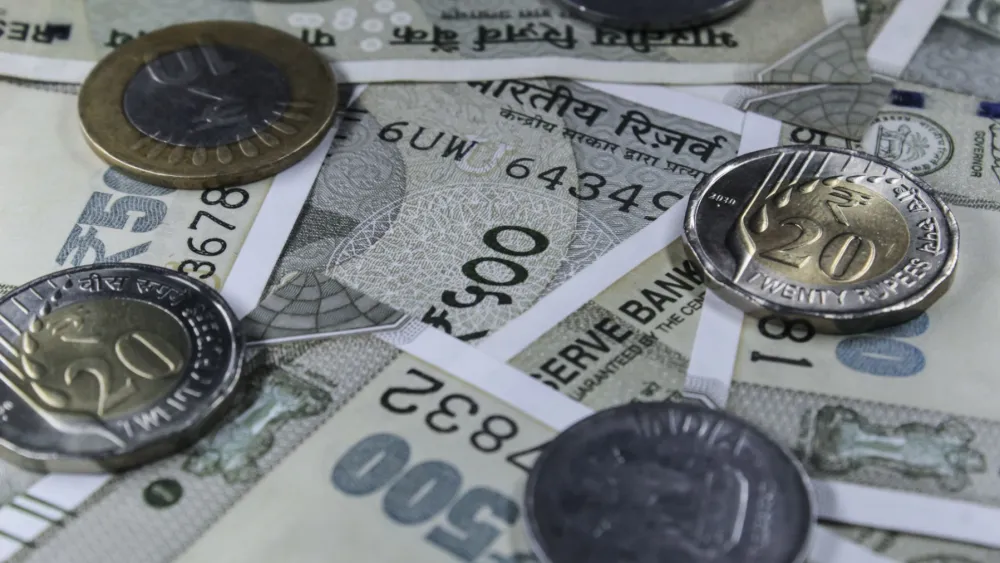
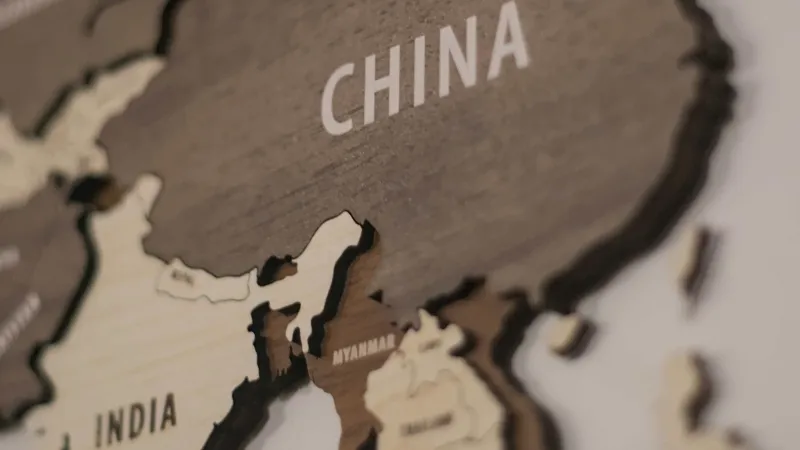
Foreign banks are finding it easier to expand in India through acquisitions and partnerships, whilst high capital requirements and intense competition continue to limit their growth in China, according to analysts.
“India is becoming easier to plan for, especially for banks willing to commit local capital or buy into an Indian platform,” Saumitra Sehgan, a partner at Roland Berger, told Asian Banking & Finance in an emailed reply to questions.
India attracted several major foreign investments in 2025, including Sumitomo Mitsui Banking Corp.'s $1.6b purchase of a 20% stake in Yes Bank.
Mitsubishi UFJ Financial Group, Inc. also agreed to pay $4.3b for a 20% stake in Shriram Finance Ltd., a nonbank lender. Emirates NBD announced a $2.75b acquisition of 60% of RBL Bank, closing the deal in June.
Sehgan said these deals showed that foreign banks increasingly regard acquisitions and partnerships as practical ways to expand in India's $3.65t banking market.
China, by contrast, has struggled to attract greater foreign participation despite easing restrictions since 2001.
Foreign banks' share of China's $70.93t banking market fell to 1.2% in 2024 from 1.5% in 2020, according to Laurent Doucet, a partner at Roland Berger.
“[Despite] waves of regulatory liberalization, the number of locally incorporated subsidiaries and foreign branches have plateaued since 2018, with a few players even exiting retail business in China due to intensive competition,” he said.
Foreign banks establishing locally incorporated units in China need at least $149m in capital, compared with $53m for wholly owned units in India, Roland Berger said.
China also allows foreign bank branches with minimum operating funds of $29.9m (RMB200m), although restrictions limit their retail banking activities.
India's foreign bank branch expansion is constrained by a World Trade Organization commitment allowing 12 more branches annually across all foreign banks.
Foreign bank units in India must also direct at least 40% of their eligible lending to priority sectors designated by the country’s central bank.
Sehgan said acquisitions require approvals from banking, securities, and competition regulators, making regulatory clearance a significant source of delays.
Jasper Yip, head of Greater China at Oliver Wyman Group, said China's data, technology, and security requirements add costs for international banks operating across multiple markets.
The differences are shaping where foreign banks see opportunities.
In China, Yip said foreign banks could use local relationships with Chinese companies expanding overseas to generate business across Hong Kong and their international networks.
“The onshore presence can be an origination engine for relationships that ultimately create value across Hong Kong and the bank's wider international network,” he said in an emailed reply to questions.
Doucet said foreign banks could also serve overseas companies entering China and provide cross-border wealth management services.
India offers opportunities in corporate banking, trade finance, foreign exchange, custody, capital markets, and wealth management, Sehgan said.
He said banks with established trade, investment, and customer relationships linked to India are best positioned to expand.
Yip said the choice between the two markets ultimately depends on each bank's ability to turn local operations into broader international business.
“The answer for an individual bank depends on its existing franchise, including its sector and client strengths, product capabilities, people on the ground, and the strength of its Hong Kong and international network,” he added.
 Read Here
 Advertise
 Sign Up