Deposit repricing and policy support shields Chinese bank margins
Loan growth slowed and fee income disappointed in Q2.
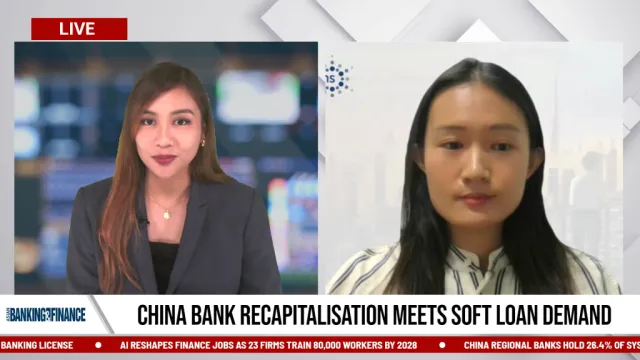
Chinese banks continue to deal with weak credit demand and retail asset-quality pressures, according to Maybank Investment Banking Group (Maybank IBG).
Deposit repricing and targeted policy support have protected Chinese banks’ margins and dividends. Capital injections have also lowered systemic risk.
“[Yet] weak credit demand, falling loan yields and retail asset-quality pressure still cap returns,” Maybank IBG’s regional research team said in a sector note on 12 October 2026.
In separate reports, both CreditSights and Morningstar said that whilst banks reported stable Q2 results, their loan growth slowed and fee income disappointed.
“The mixed results reflected a sequential increase in net interest margin (NIM), but weak credit demand clouds the recovery outlook,” Iris Tan, senior equity analyst at Morningstar, said in an August 2026 analyst note.
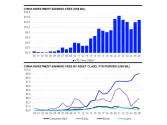
The banks’ first half loan growth was the slowest since at least 2019, according to CreditSights.
 Read Here
 Advertise
 Sign Up